素材包 · 2026-10-22
内容素材包 · 2026-10-22
基于 arr.club 当日 published signals(20 条),ready-to-copy,John 过目即发。
生成时间:2026-10-23 08:09(北京时间)
Tractian — Tractian crossed $100M annualized revenue and raised $130M Series D at $1.4B valuation
- ARR:$100M
- 来源:https://lnkd.in/p/gf7Mv8DH
X(≤280 字符)
Tractian is the new gold standard for industrial AI.

They crossed $100M in annualized revenue, growing 90% YoY. They raised $130M at a $1.4B valuation.

Practical hardware-enabled software wins.

Tracked live at arr.club
字符数:221
LinkedIn
Tractian crossed **$100M** in annualized revenue and raised a **$130M** Series D at a **$1.4B** valuation. This milestone cements their position as a standout in the industrial AI space and marks them as the latest unicorn to emerge from Y Combinator.

I have watched the industrial tech sector struggle to bridge the gap between hardware sensors and actionable software, but Tractian’s execution proves that the market is ready for high-fidelity predictive maintenance. Growing at **90%** year over year at this scale is a testament to the urgency of their value proposition.

Here is why this matters:

1. The wedge is brutally practical. By targeting unplanned downtime in sectors like food and beverage, they solved a high-cost pain point that justifies immediate enterprise adoption.
2. They successfully expanded into critical infrastructure. Their growth in AI data centers shows that as the physical footprint of compute grows, the demand for reliable, sensor-driven maintenance will only accelerate.
3. They are successfully bringing AI to the physical world. Moving beyond simple monitoring to predictive, actionable insights is the only way to build a durable, multi-billion dollar industrial software business.

The shift toward digitizing legacy industrial equipment is no longer a theoretical trend; it is a massive, capital-efficient engine for growth. I track verified ARR milestones like this daily at arr.club.
数据卡片
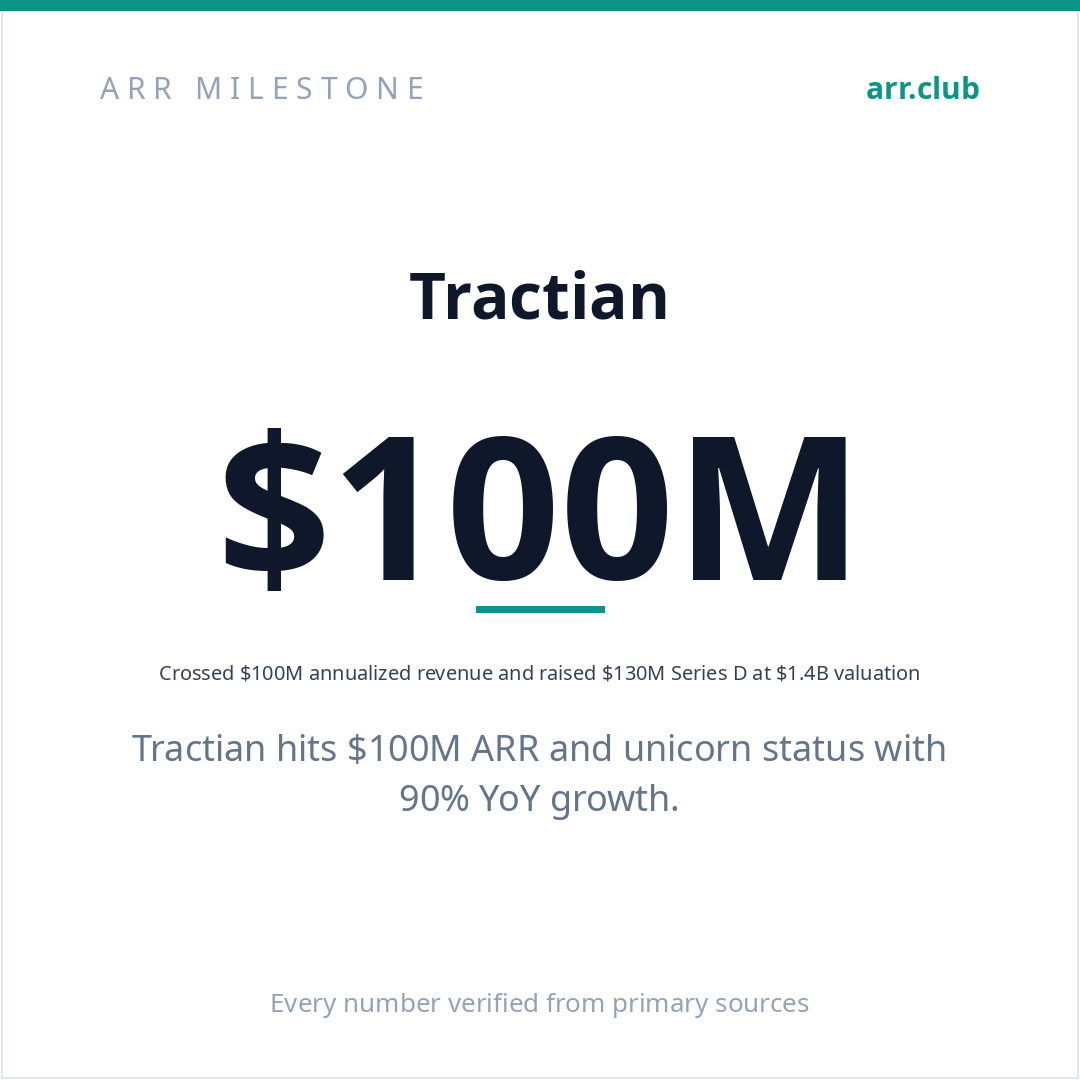
Thinking Machines — Thinking Machines Lab surpassed $100M revenue run-rate on Tinker
- ARR:$100M+
- 来源:https://aimagazine.com/news/thinking-machines-lab-hits-a-us-100m-run-rate-on-tinker
X(≤280 字符)
Thinking Machines Lab crossed a $100M annual revenue run-rate on Tinker.

This is the proof investors demanded. The lab transitioned from a talent magnet to a real business. Valuation expectations are adjusting to reality.

Tracked live at arr.club
字符数:248
LinkedIn
Thinking Machines Lab surpassed a **$100M** annual revenue run-rate on Tinker, its fine-tuning API. This milestone marks the company’s transition from a pure research talent magnet to a commercial powerhouse.

I have watched this space closely, and the shift from hype to utility is finally showing in the financials. When a company moves from a **$2 billion** seed round—raised before it even had a product—to a **$100M** run-rate in such a short window, it signals that the infrastructure layer is maturing faster than many skeptics anticipated.

Here is why this matters:

1. Tinker’s traction proves that enterprises are moving beyond simple inference. By allowing companies to fine-tune open models with custom training loops, Thinking Machines captured the demand for specialized, low-latency performance, evidenced by results like a **50%** reduction in search latency for early users.
2. The infrastructure moat is real. With a **one gigawatt** commitment from NVIDIA for Vera Rubin systems, the lab has secured the compute necessary to scale its **975-billion-parameter** models, creating a feedback loop between hardware access and revenue growth.
3. Valuation discipline is returning to the market. Investors are currently weighing a **$1 billion** round at a **$40 billion-plus** valuation, a notable step down from the **$50 billion** target the lab sought in late **2025**. This confirms that even for the most hyped labs, revenue proof is now the primary driver of deal terms.

I track verified ARR milestones like this daily at arr.club.
数据卡片
Higgsfield — Higgsfield grew B2B revenue 10x since January as enterprise usage doubled monthly
- ARR:(未披露)
- 来源:https://www.linkedin.com/posts/amashrabov_higgsfields-enterprise-usage-is-growing-over-share-7518452519807905792--Hio/
X(≤280 字符)
Higgsfield grew B2B revenue 10x since January. Enterprise usage climbed 100%+ month-over-month. One account expanded from $1,000 to $6,000,000 in 6 months.

Enterprise video generation is no longer an experiment. It is a core budget line.

Tracked live at arr.club
字符数:264
LinkedIn
Higgsfield grew its B2B revenue **10x** since January, proving that enterprise video generation has moved from an experimental budget line to a core operational necessity. I have watched many AI companies struggle to bridge the gap between viral consumer adoption and enterprise stickiness, but Higgsfield is successfully leveraging its product velocity to drive massive account expansion.

The speed of this transition is what caught my attention:

1. Enterprise usage grew over **100%** month-over-month, signaling that the product is becoming deeply embedded in marketing and studio workflows.
2. Expansion dynamics are aggressive, with nearly **50%** of accounts growing within **2** months of signing.
3. The ceiling for these accounts is high, evidenced by one specific client that scaled from **$1,000** to **$6,000,000** in just **6** months.

When a company sees this level of compounding usage, the focus shifts from product-market fit to pure execution. Higgsfield is now scaling its go-to-market team to capture the demand they’ve generated, signaling that they are no longer just a consumer breakout, but a serious enterprise player. The ability to turn a small pilot into a multi-million dollar contract in half a year is the kind of signal that separates the winners in the current AI landscape.

I track verified ARR milestones like this daily at arr.club.
数据卡片
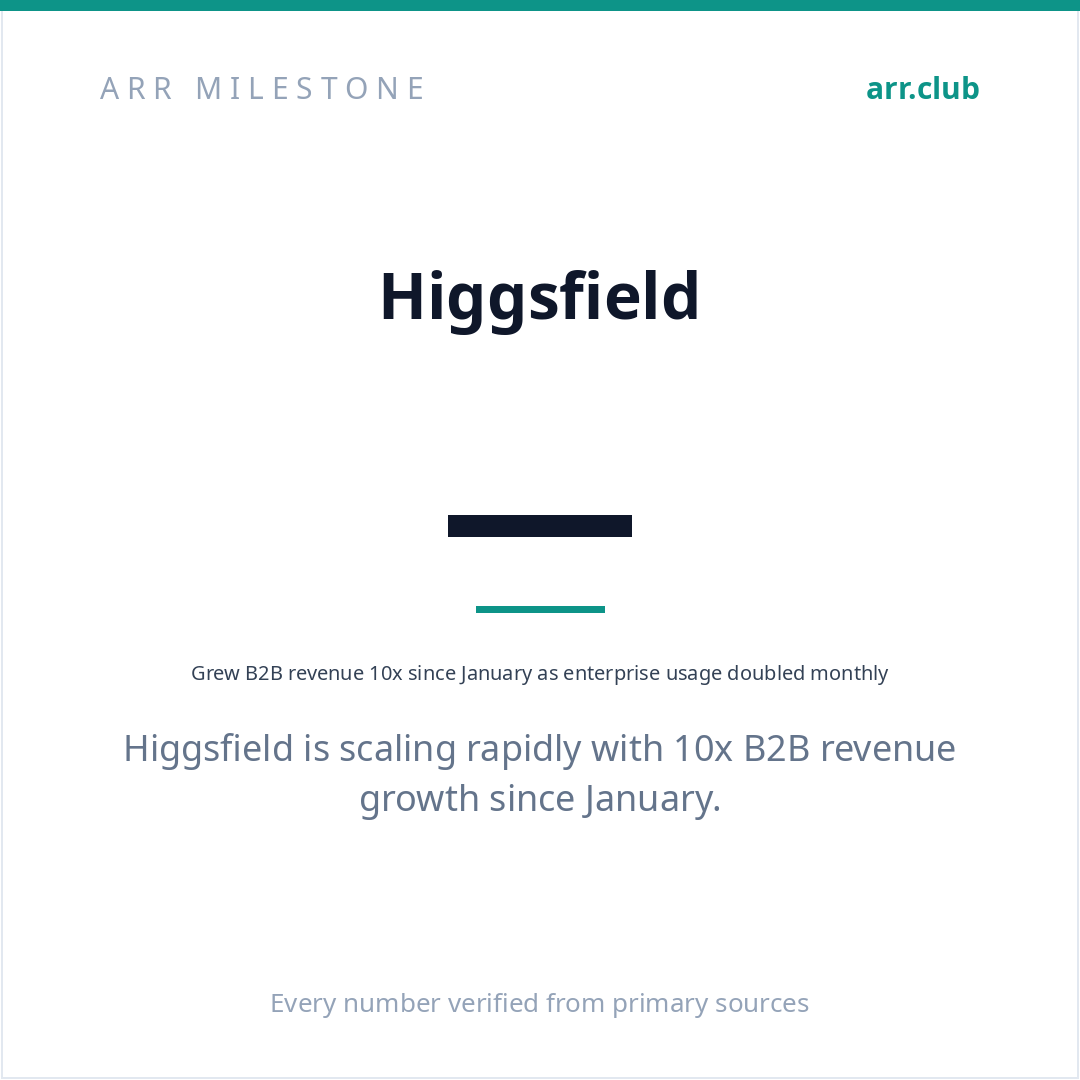
Reach AI — Reach AI grew to $1.4M ARR in 13 months, bootstrapped
- ARR:$1.4M
- 来源:https://www.linkedin.com/posts/zevelez_ive-spent-10k-hosting-founder-dinners-share-7518719776152616961-LKOg/
X(≤280 字符)
Reach AI reached $1.4M ARR in 13 months, bootstrapped. They hit $1M ARR in 11 months, adding $400K in 2 months.

Killing a channel with positive ROI because it lacked efficiency is the rigor that sustains growth.

Tracked live at arr.club
字符数:238
LinkedIn
Reach AI reached **$1.4M** ARR in just **13** months, all while remaining essentially bootstrapped. This growth trajectory, which saw the company add **$400K** ARR in the **2** months following their **$1M** milestone, highlights a rare level of capital efficiency in today’s market.

I’ve been tracking the GTM rigor behind these numbers, and it comes down to a willingness to kill channels that don't fit the buyer journey. Here is what stands out:

1. High-touch events like founder dinners, despite generating **$200K+** in influenced annual contract value, underperformed compared to other channels. The team realized that spending **$10K+** to initiate conversations is far less effective than using those events to accelerate existing ones.
2. The company is now doubling down on high-intent signals by combining website visitor identification with search data. They are prioritizing prospects who have already demonstrated a clear need, rather than casting a wide net.
3. Channel timing is critical. While SEO and AI search offer superior unit economics, they often don't hit their stride until a company crosses the **$5M** ARR mark. Trying to force these channels too early can lead to wasted resources.

Bootstrapped SaaS compounding at this pace requires the discipline to pivot quickly when the data suggests a better path. I track verified ARR milestones like this daily at arr.club.
数据卡片
Cuttable — Cuttable grew revenue 20x in a year and raised $20M Series A
- ARR:(未披露)
- 来源:https://www.linkedin.com/posts/jethrocohen_i-have-been-really-fortunate-to-work-closely-share-7518808050053484544-2p2t/
X(≤280 字符)
Cuttable grew revenue 20x in the last year and raised a $20M Series A.

They are bottling agency-grade thinking rather than just raw generation. This is the system performance marketers reach for as AI changes ad creative.

Tracked live at arr.club
字符数:248
LinkedIn
Cuttable just raised a **$20 million** Series A led by Airtree after growing revenue more than **20x** in the last year. This is a masterclass in moving beyond simple generative AI to solve a specific, high-stakes problem for performance marketers.

Most AI tools focus on the cost of creation, but Cuttable focused on the quality of outcomes. By analyzing **280,000** ads and **$260 million** in Meta spend, they identified that only **1%** of ads drive half of all revenue. Their platform now automates the "learning" process, ensuring that every campaign informs the next rather than starting from scratch.

Here is why this signal stands out:

1. The team is leveraging a massive data moat. By processing **$260 million** in ad spend across **440** ecommerce brands, they have built a feedback loop that raw generative models cannot replicate.
2. They are solving the "cheap but not good" trap. Most AI ad tools flood the market with noise, but Cuttable is positioning itself as a performance engine that helps brands find the **1** winning ad out of every **42** attempts.
3. The pedigree is undeniable. With a founder who previously sold a company for **$2 billion** and a cap table featuring repeat investors who have backed the team **4** times, the execution risk is significantly lower than the average AI startup.

Cuttable is proving that the real value in AI isn't just generating content—it’s bottling the agency-grade strategy that actually moves the needle. I track verified ARR milestones and growth signals like this daily at arr.club. #AI #SaaS
数据卡片
Kleo — Kleo hit $1M ARR in under six months
- ARR:$1M
- 来源:https://www.linkedin.com/posts/maittreykhedekar_kleo-reached-1m-in-arr-in-under-6-months-share-7518563840930967552-xoJF/
X(≤280 字符)
Kleo hit $1M ARR in under 6 months.

They built an audience of 480,000 followers before launching a single line of code. Distribution is the ultimate moat for AI products.

Tracked live at arr.club
字符数:197
LinkedIn
Kleo reached **$1M** in ARR in under **six** months. This is a masterclass in distribution-led growth, proving that the most effective customer acquisition strategy is building an audience before you ever write a line of code.

The founders—Lara Acosta, Jake Ward, and Cam Trew—did not rely on paid ads or influencer campaigns to scale. Instead, they leveraged their combined **480,000** followers to create an immediate, high-intent feedback loop. By the time they launched their AI writing assistant, they were already solving a known pain point for the exact people who trusted their expertise.

Here is why this matters:

1. Distribution is the new moat. When you own the channel, you bypass the rising costs of traditional customer acquisition.
2. Product-market fit is easier to find when you are your own target user. They built a tool to solve a problem they faced daily, ensuring the utility was clear from day one.
3. Launch day should be a formality, not a gamble. By the time they introduced the product, they had already spent years building the trust required to convert followers into paying customers.

The audience-first playbook is becoming the standard for lean, high-velocity SaaS. Kleo didn't just build a tool; they built a business on top of a pre-existing community. I track verified ARR milestones like this daily at arr.club.
数据卡片
YGO — YGO reached $1M ARR in six months, raised €8M Series A
- ARR:(未披露)
- 来源:https://www.linkedin.com/posts/ventech-leads-8m-series-a-in-ygo-ai-infras-ugcPost-7518573736707608576-l7dn/
X(≤280 字符)
YGO reached $1M ARR in 6 months and raised an €8M Series A.

Travel infrastructure is the ultimate pick-and-shovel play for AI agents. Suppliers are desperate to bypass intermediaries and own their inventory again.

Tracked live at arr.club
字符数:240
LinkedIn
YGO reached **$1M** ARR in just **six** months and announced an **€8M** Series A led by Ventech. This is a classic example of a pivot done right, moving from a consumer-facing app to the critical infrastructure layer that travel suppliers desperately need.

The travel industry is currently held back by legacy systems that weren't built for an AI-first world. By positioning themselves as the orchestration layer between suppliers and AI agents, YGO is capturing the value that usually leaks to intermediaries.

Here is why this move matters:

1. Speed to market: Hitting **seven-figure** ARR in **six** months proves that the pain point for suppliers is acute and immediate.
2. Strategic leverage: By enabling direct sales, they help suppliers reclaim the **15–25%** commission typically lost to online travel agencies.
3. Proven scale: They have already processed over **€15M** in bookings, signaling that their infrastructure is robust enough for major players like Condor Airlines.

The team’s decision to pivot away from a consumer model in **2023** after realizing the limitations of the current inventory landscape was a high-conviction bet. They previously raised **€2.5M** in **August 2024**, and this new capital provides the runway to solidify their position as the primary bridge for AI-ready travel inventory.

I track verified ARR milestones like this daily at arr.club.
数据卡片
ComplyJet — ComplyJet hit $10M ARR as a profitable bootstrapped company
- ARR:$10M
- 来源:https://www.linkedin.com/posts/upvarma_a-100-to-500-million-dollar-exit-to-the-share-7518683345342636032-nLI5/
X(≤280 字符)
ComplyJet reached $10M ARR.

It achieved this while remaining profitable and fully bootstrapped. Rejecting the venture scoreboard to build a lean, efficient machine is a masterclass in capital discipline.

Tracked live at arr.club
字符数:230
LinkedIn
ComplyJet reached **$10M** ARR as a profitable, bootstrapped company. In a category defined by massive venture burn, this milestone is a masterclass in capital efficiency.

I have watched the compliance automation space become crowded with heavily funded incumbents, but ComplyJet proved that a lean, founder-led model can still capture significant market share. By rejecting the venture scoreboard, they maintained total control over their product roadmap and pricing strategy.

Here is why this matters:

1. Profitability is the ultimate moat. While competitors chase growth at any cost, ComplyJet built a sustainable engine that doesn't rely on external capital to survive market volatility.
2. Pricing simplicity wins. By offering a flat fee starting at **$5,000** per year instead of complex per-seat models, they lowered the barrier to entry for the exact startups that find legacy GRC tools too expensive.
3. Product-led efficiency scales. Integrating with over **100** tools to automate evidence collection allowed them to reach this scale without the massive sales overhead typical of the industry.

The real test for ComplyJet will be maintaining this momentum as the GRC market consolidates. However, hitting **$10M** ARR without a single dollar of outside funding is an elite achievement that few SaaS companies ever reach.

I track verified ARR milestones like this daily at arr.club.
数据卡片
Blacksmith — Blacksmith grew ARR 17x and raised Series C at $1B valuation
- ARR:(未披露)
- 来源:https://www.blacksmith.sh/blog/series-c
X(≤280 字符)
Blacksmith grew ARR 17x since January and raised a Series C at a $1B valuation. Weekly CI jobs jumped from 5M to 90M.

This is a direct bet on the agent-coding supercycle. The CI infrastructure market is repricing fast.

Tracked live at arr.club
字符数:245
LinkedIn
(生成失败:RuntimeError: LLM call failed 3 times (linkedin_post-retry): 503 Server Error: Service Unavailable for url: https://generativelanguage.googleapis.com/v1beta/openai/chat/completions)
数据卡片
Commander — Commander tripled ARR in 2026 selling AI to waste haulers
- ARR:(未披露)
- 来源:https://www.waste360.com/industry-insights/commander-the-ai-sales-engine-of-wastetech-triples-arr-in-2026-and-names-dave-meizlik-president-coo
X(≤280 字符)
Vertical AI wins by digitizing the unsexy. Commander grew ARR 300% in 2026 by automating sales for waste haulers. They already serve 100 companies, including 3 of the 8 largest in North America. The wedge is working.

Tracked live at arr.club
字符数:242
LinkedIn
Commander tripled its ARR in 2026 by applying AI to the waste, recycling, and scrap hauling industry. This growth proves that vertical AI is finding its fastest traction in sectors that legacy software ignored.

The waste industry is fragmented and historically relied on manual sales processes, leaving a massive opening for a dedicated revenue layer. Commander’s ability to land **3** of the **8** largest haulers in North America in such a short window is a testament to the product-market fit of their AI-powered prospecting and CRM tools.

Here is why this signal matters:

1. Vertical AI wins by solving specific operational gaps. By identifying over **$70 million** in new revenue opportunities for its **100+** customers, Commander moved from a "nice-to-have" tool to a core revenue driver.
2. Operational expertise accelerates GTM. Bringing in a President and COO who previously scaled a company past **$100 million** in revenue provided the necessary structure to turn a wedge product into a repeatable sales engine.
3. The "unsexy" industry thesis remains the most reliable path to scale. Commander’s **300%** growth in **2026** shows that when you digitize a manual, high-friction sales process in a massive, overlooked market, the adoption curve is steep.

I track verified ARR milestones like this daily at arr.club.
数据卡片
Hebbia — Hebbia tripled new ARR quarter over quarter in record Q3
- ARR:(未披露)
- 来源:https://www.linkedin.com/posts/sivulka_q3-was-the-biggest-quarter-in-hebbias-history-share-7518699547368534016-pvcW/
X(≤280 字符)
Hebbia tripled new ARR QoQ and grew daily active users 5x in Q3. Gross revenue retention stayed above 95%.

This is the enterprise AI compounding story in miniature: land, expand, and keep customers coming back daily.

Tracked live at arr.club
字符数:243
LinkedIn
(生成失败:RuntimeError: LLM call failed 3 times (linkedin_post): 503 Server Error: Service Unavailable for url: https://generativelanguage.googleapis.com/v1beta/openai/chat/completions)
数据卡片
WP SEO AI — WP SEO AI hit €20M ARR serving more than 2,500 companies
- ARR:$20M
- 来源:https://lnkd.in/p/gkm-GyPs
X(≤280 字符)
(生成失败:RuntimeError: LLM call failed 3 times (x_post): 503 Server Error: Service Unavailable for url: https://generativelanguage.googleapis.com/v1beta/openai/chat/completions)
LinkedIn
WP SEO AI reached **€20M** in ARR this week, proving that Generative Engine Optimization (GEO) is rapidly moving from an experimental budget to a core line item. The Dutch platform now serves more than **2,500** companies, signaling a massive shift in how businesses prioritize visibility in the age of AI-generated answers.

I believe this milestone matters for three specific reasons:

1. The hybrid model works. By pairing autonomous AI agents with dedicated human specialists, they moved beyond simple SaaS churn and secured accountability for actual revenue results.
2. The "front page" has changed. With AI answers now dominating discovery, companies are shifting marketing spend away from traditional SEO toward platforms that guarantee citation within AI-generated responses.
3. Speed to scale is accelerating. Launching in **2023** and hitting this revenue level so quickly demonstrates that WordPress-native workflows are the fastest path to capturing SMB market share.

The market is clearly rewarding those who build for the reality of AI Overviews rather than just legacy search rankings. I track verified ARR milestones like this daily at arr.club.
数据卡片
OpusClip — OpusClip hit $50M+ ARR with 20M users turning long video into shorts
- ARR:$50M+
- 来源:https://www.linkedin.com/posts/yzopus_3-years-ago-opusclip-was-3-people-making-ugcPost-7518709518793408512-jUSB/
X(≤280 字符)
OpusClip passed $50M+ ARR with 300,000 paying customers and 20M users.

Three years of elite SaaS velocity. The moat is a data flywheel where every generated clip trains the model on what performs.

Tracked live at arr.club
字符数:223
LinkedIn
OpusClip reached **$50M+** ARR just three years after starting as a **3**-person team. This is elite SaaS velocity that separates the winners from the noise in the crowded AI video space.

The company scaled to **20 million** users and **300,000** paying customers by solving a specific, high-friction pain point for creators and enterprises like NVIDIA and Visa. Their success proves that deep operator experience—the founders previously ran a **500**-person talent agency—is often the best predictor of product-market fit.

Here is why this milestone matters:

1. Distribution is the ultimate moat. By embedding themselves into the workflow of creators and large enterprises, they built a data flywheel where every generated clip improves the model’s performance.
2. Founder evolution is a prerequisite for scale. The CEO’s transition from a **100%** builder to a manager of a **100**-person team, supported by executive coaching, was a critical factor in maintaining this growth trajectory.
3. Capital efficiency remains key. Despite raising **$68 million** in total funding, including a **$20 million** Series B, the company’s ability to convert that capital into **$50M+** ARR demonstrates a disciplined approach to growth that many AI startups currently lack.

I track verified ARR milestones like this daily at arr.club.
数据卡片
SCAILE — SCAILE reached €1M ARR four months after launch
- ARR:$1M
- 来源:https://lnkd.in/p/gxyGgs3r
X(≤280 字符)
SCAILE reached €1M ARR just 4 months after launch.

They serve 100+ brands including Porsche with AI search infrastructure. This is extreme velocity. It proves brands are already reallocating budgets to win in the AI answer engine era.

Tracked live at arr.club
字符数:261
LinkedIn
SCAILE reached **€1M** ARR just **four** months after launch. This is extreme velocity, even by current AI standards, and it signals a fundamental shift in how brands approach digital discovery.

The company builds AI search-visibility infrastructure, helping brands secure placement within generative engines like ChatGPT and Perplexity. I believe this category—Generative Engine Optimization—is becoming a critical line item for marketing budgets as consumer behavior moves away from traditional search results.

Here is why this milestone matters:

1. The speed of adoption proves that the "AI answer" is already a high-stakes battlefield for enterprise brands.
2. With **100+** brands like Porsche and Freenet already on board, the product-led motion is clearly resonating with teams feeling the immediate urgency of AI-driven traffic.
3. Reaching a **seven-figure** run rate this quickly without typical venture-scale burn suggests that the infrastructure layer of the AI transition is monetizing faster than the application layer.

When brands realize their visibility is being mediated by LLMs, they stop asking if they need this tooling and start asking how much it costs. SCAILE is capturing that demand before the market even fully matures.

I track verified ARR milestones like this daily at arr.club.
数据卡片
Dapta — Dapta hit $4M+ annual revenue and raised $6M seed
- ARR:$4M
- 来源:https://infotechlead.com/tech/vc-funding-deals-dapta-marklo-leela-98970
X(≤280 字符)
Dapta hit $4M in annual revenue and raised $6M in seed funding. Revenue doubled in 6 months as their AI agent passed 200,000 users.

Founder-led distribution is the new moat in SMB AI.

Tracked live at arr.club
字符数:210
LinkedIn
Dapta reached **$4M** in annual revenue and secured a **$6M** seed round led by Chingona Ventures. This milestone confirms that the most successful AI agents are currently being built by following the money rather than just the technology.

The company’s pivot from a no-code API platform to an AI sales agent, Dapti, proved that listening to your paying customers is the fastest path to scale. By focusing on Spanish-speaking SMB owners in the US and major players like Mercado Libre, they found a massive, underserved market.

Here is why this signal matters:

1. Velocity is the ultimate validator. The company doubled its annual revenue in just **six months**, proving that their AI agent provides immediate, tangible ROI for SMBs.
2. Distribution is the new moat. With **200,000** users and growth driven primarily by the founder’s social channels rather than paid acquisition, they are proving that organic reach is a sustainable advantage in the crowded AI space.
3. The total funding of **$7.4M** reflects a clear bet on the future of SMB operations, where AI agents will soon be as essential as a business phone number or website.

Dapta’s success highlights that the "agentic" era is moving beyond hype and into high-utility, high-growth territory. I track verified ARR milestones like this daily at arr.club.
数据卡片
Even Healthcare — Even Healthcare raised $50M Series B at $300M valuation to build hospitals
- ARR:(未披露)
- 来源:https://techcrunch.com/2026/10/19/khosla-ventures-doubles-down-on-even-healthcare-to-challenge-indias-hospital-economics/
X(≤280 字符)
Even Healthcare raised $50M at a $300M valuation. This tripled its valuation in 18 months.

The model works by aligning doctor incentives with patient outcomes rather than volume. It is a massive bet on vertical integration in Indian healthcare.

Tracked live at arr.club
字符数:271
LinkedIn
Even Healthcare raised a **$50 million** Series B at a **$300 million** valuation, tripling its valuation in just **18 months**. This move signals a massive shift in how we should view healthcare infrastructure in emerging markets.

I believe the most compelling aspect of this deal isn't just the capital, but the fundamental change in incentives. By moving from a traditional fee-for-service model to an outcome-based approach, Even is proving that aligning doctor compensation with patient health—rather than procedure volume—is a viable path to profitability.

Here is why this model is gaining traction:

1. Operational efficiency is the new moat: With unplanned readmission rates under **1%** compared to the **8–15%** industry benchmark, the data proves that better care is cheaper care.
2. Vertical integration works: By building their own hospitals, they captured enough margin to turn their first **two** Bengaluru locations profitable within **one** year of opening.
3. Scalability through density: The company is now deploying **five** more hospitals in **six** months, aiming to place a facility within **five** kilometers of every family in the city.

The company has now raised over **$120 million** to scale this contrarian bet across India. It is a rare example of a managed-care provider successfully transitioning into a capital-intensive hospital operator. I track verified ARR and funding milestones like this daily at arr.club.
数据卡片
Pillar — Pillar hit €4M ARR with 1,000+ customers
- ARR:$4M
- 来源:https://lnkd.in/p/gYePFVSm
X(≤280 字符)
Pillar reached €4M ARR with 1,000+ customers. It grew from €3M ARR in one month.

Vertical fintech is winning in construction. The wedge is working because the market was waiting for purpose-built software.

Tracked live at arr.club
字符数:232
LinkedIn
Pillar just hit **€4M** in ARR, marking a significant acceleration for the Italian construction fintech. This jump from **€3M** to **€4M** in just **1** month proves that the industry is finally ready to abandon paper-based workflows for purpose-built financial software.

I have been watching the vertical fintech space closely, and Pillar’s trajectory confirms that digitizing the construction sector’s cash flow is a massive, untapped opportunity. When a company adds **€1M** in ARR in such a short window, it signals that the product-market fit is not just theoretical—it is operational.

Here is why this matters:

1. Velocity in vertical SaaS is often driven by solving the most painful administrative bottlenecks, and Pillar’s focus on invoicing and payments for contractors is clearly hitting a nerve.
2. The company’s ability to scale to **1,000+** customers demonstrates that their wedge is repeatable across a fragmented market.
3. With **€12M** in seed funding and a previous **€3.2M** pre-seed round, they have the balance sheet to defend their lead as they expand beyond Italy.

Construction remains one of the last major industries to undergo a digital transformation. Pillar is proving that if you build the right infrastructure, the adoption curve can be incredibly steep.

I track verified ARR milestones like this daily at arr.club. #Fintech #SaaS
数据卡片
Greptile — Greptile raised $50M Series B at $750M valuation to end the war on bugs
- ARR:(未披露)
- 来源:https://www.greptile.com/blog/series-b
X(≤280 字符)
Greptile is the new standard for code validation.

They raised a $50M Series B at a $750M valuation. This is a 4x jump from their $180M valuation in September 2025. They now review over 1% of all GitHub PRs daily for teams like Nvidia and Coinbase.

Tracked live at arr.club
字符数:274
LinkedIn
Greptile just raised a **$50 million** Series B at a **$750 million** valuation, marking a **4x** jump from its **$180 million** valuation just over a year ago. In a crowded AI coding market, this round proves that the real value isn't just in writing code, but in the independent validation layer that ensures it actually works.

I’ve been watching the race to automate code review, and Greptile’s architectural approach is the clear differentiator. By indexing the entire codebase rather than just reviewing diffs, they have captured a massive footprint in the developer workflow.

Here is why this matters:

1. Scale is the ultimate moat. Reviewing over **1%** of all GitHub pull requests daily provides a data advantage that is nearly impossible for competitors to replicate.
2. Enterprise trust is the new currency. When companies like Nvidia and Coinbase rely on your infrastructure to validate their production code, you have moved from a "nice-to-have" tool to a critical piece of the software development lifecycle.
3. The bottleneck has shifted. As AI agents accelerate code generation, the demand for automated, high-fidelity security and architectural oversight has become the primary constraint for engineering teams.

The jump from a **$25 million** Series A in September 2025 to this **$50 million** Series B shows how quickly the market is consolidating around winners who can prove deep technical utility. I track verified ARR and funding milestones like this daily at arr.club.
数据卡片
Legora — Legora raised $550M Series E at $8.8B valuation
- ARR:(未披露)
- 来源:https://techcrunch.com/2026/10/21/legal-ai-startup-legora-raises-550m-series-e-at-8-8b-valuation/
X(≤280 字符)
Legora hit $200M ARR after doubling in under 6 months. It raised $550M at an $8.8B valuation.

Legal AI is now a capital-intensive arms race. The market is rewarding scale and speed over everything else.

Tracked live at arr.club
字符数:229
LinkedIn
Legora just reached an **$8.8 billion** valuation after closing a **$550 million** Series E round. This milestone confirms that the legal AI sector has moved beyond simple assistants into high-value, automated workflows.

I view this as a critical signal for the maturity of applied AI. When a company doubles its ARR from **$100 million** to over **$200 million** in under **six months**, it proves that legal professionals are ready to pay for services that complete actual work rather than just drafting suggestions.

Here is what this tells me about the current market:

1. Velocity is the new currency. Legora increased its valuation by more than **50%** in roughly **six months**, showing that investors are willing to pay a premium for companies that demonstrate hyper-growth at scale.
2. The legal AI category is now one of the most heavily capitalized corners of the industry. With two major players now reporting ARR above **$200 million**, the market is effectively bifurcating into a race for dominance between the top incumbents.
3. Revenue scale is the primary benchmark for valuation. While Legora and its primary rival are matched on revenue, the valuation gap suggests that investors are still weighing product differentiation and market positioning heavily alongside raw ARR growth.

The speed at which these companies are scaling is unprecedented for the legal tech vertical. I track verified ARR milestones like this daily at arr.club. #LegalAI #SaaS
数据卡片
Flapping Airplanes — Flapping Airplanes raised $1B Series A at $6B valuation
- ARR:(未披露)
- 来源:https://techcrunch.com/2026/10/21/year-old-ai-lab-flapping-airplanes-raises-1b-at-a-6b-valuation/
X(≤280 字符)
Flapping Airplanes raised a $1B Series A at a $6B valuation. This quadrupled their $1.5B valuation from just 9 months ago.

Capital is flooding into post-scaling-law infrastructure bets. The market is pricing in massive efficiency gains.

Tracked live at arr.club
字符数:263
LinkedIn
Flapping Airplanes raised a **$1 billion** Series A at a **$6 billion** valuation, marking one of the most aggressive capital deployments I have seen for a **one-year-old** AI lab. This round arrived just **nine months** after their **$180 million** seed round, which valued the company at **$1.5 billion**.

The speed of this valuation jump—quadrupling in less than a year—signals that investors are betting heavily on the team’s thesis that data efficiency is the next frontier for AI infrastructure. While the company has not disclosed revenue, the presence of Nvidia and a tier-one syndicate on the cap table suggests the market is prioritizing technical breakthroughs in compute optimization over immediate commercialization.

Here is what this move tells me about the current AI landscape:

1. Capital is aggressively chasing "post-scaling-law" bets, prioritizing infrastructure that reduces the massive costs associated with training large models.
2. The "young person's AGI lab" narrative is attracting unprecedented institutional support, with top-tier firms doubling down on founders who can bridge the gap between academic research and hardware utilization.
3. Valuation premiums are now being driven by the potential for architectural efficiency rather than traditional SaaS metrics, as investors look for ways to make AI models economically viable for the real economy.

I track verified ARR milestones and funding signals like this daily at arr.club.
数据卡片
早期项目内参 · 2026-10-22
过去 7 天融资事件 + 新增早期公司扫描,按 tier-1 机构/轮次/赛道打分取 Top 5。仅 John 可见。
1. Dapta
- 一句话: 为中小企业提供通过 WhatsApp 和电话自动响应、筛选并安排入站线索的 AI 销售代理。
- 融资: 600 万美元,领投/参投方:未披露。
- 为什么值得看: 公司已实现 400 万美元以上的年度经常性收入 (ARR),在 AI 销售自动化领域展现出极强的产品市场匹配度 (PMF) 和增长势头。
- 跟进动作: 建议深入调研其在 WhatsApp 生态中的获客效率及留存数据。
2. YGO
- 一句话: 旅游行业的 AI 基础设施层,将航空公司、酒店和旅行社的库存结构化,使其适配 AI 代理进行预订。
- 融资: 800 万欧元,领投/参投方:未披露。
- 为什么值得看: 仅用六个月即达到 100 万美元 ARR,切中了旅游行业数据碎片化、难以被 AI 调用这一核心痛点。
- 跟进动作: 建议评估其与主流旅游分销系统 (GDS) 的集成深度及壁垒。
3. Tolan
- 一句话: AI 驱动的伴侣与聊天机器人平台,允许用户与可定制的虚拟人格进行互动。
- 融资: 3000 万美元,领投/参投方:USV, Khosla。
- 为什么值得看: 拥有 USV 和 Khosla 等顶级机构背书,处于 AI 消费级应用的前沿,累计融资额已达 1 亿美元。
- 跟进动作: 建议分析其用户留存数据及在同类 AI 社交产品中的差异化竞争优势。
4. Cuttable
- 一句话: AI 广告平台,可将品牌现有资产转化为高性能广告,并根据每场活动的反馈进行自我学习优化。
- 融资: 2000 万美元,领投/参投方:未披露。
- 为什么值得看: 在一年内实现了 20 倍的收入增长,证明了其 AI 驱动的广告创意生成与优化方案在市场上的强劲需求。
- 跟进动作: 建议对比其与现有广告自动化工具的 ROI 表现差异。
5. Qualitate
- 一句话: 针对基础研究的持续智能系统,通过 AI 主持的专家访谈,将专家观点转化为投资和企业团队可用的结构化情报。
- 融资: 2500 万美元,领投/参投方:未披露。
- 为什么值得看: 今年收入运行率增长 10 倍,通过 AI 替代传统人工访谈流程,显著提升了投研领域获取专家洞察的效率。
- 跟进动作: 建议找创始人聊聊其 AI 访谈的深度及数据结构化的准确性。
每日文章
- `2026-10-22-free.skipped.md`